
Self-employed people
No employer sick pay at all. If you can't work, nothing comes in. Income protection is your safety net.

Monthly support if illness or injury stops you working.
Start your income protection quote online.
Protect what matters
Your earnings keep everyday life moving. Here’s where regular financial support could make a difference if illness or injury means you can't work.
No employer sick pay at all. If you can't work, nothing comes in. Income protection is your safety net.
If your household depends on one salary, losing it, even temporarily, can be catastrophic.
Mortgage, dependants, school fees. The bills don't pause because you're unwell.
Many employers only pay full salary for a few months. After that, you're on your own.
"I'm a freelance designer. There's no safety net if I can't work. This policy is the closest thing I have to an employer."
Sarah, LondonIncome Protection
When work has to wait
The difference income protection makes, month by month.
Start your quote online, then our FCA regulated advisers can recommend the right deferred period, policy definition, and cover amount for your occupation and income. No hard sell.
Weeks 1 to 4
Employer sick pay, if you have it.
Months 2 to 6
SSP kicks in, just £116 a week. Barely covers the food shop.
Month 7+
SSP ends. Savings? Benefits? Stress. The bills keep coming.
Deferred period
Usually 4 or 13 weeks, matched to when your employer sick pay runs out.
Then...
Policy pays you up to 70% of your salary every month, tax-efficiently.
Until...
You return to work, reach retirement, or the policy term ends. You decide.
No employer sick pay at all. If you can't work, nothing comes in. Income protection is your safety net.
If your household depends on one salary, losing it, even temporarily, can be catastrophic.
Mortgage, dependants, school fees. The bills don't pause because you're unwell.
Many employers only pay full salary for a few months. After that, you're on your own.
Pay for 1 to 2 years max, lower premiums
A good option if you want to cover the gap until your savings would run out, or bridge a period before long-term benefits kick in. Lower cost, but limited duration.
Pay until retirement if needed, most comprehensive
The gold standard of income protection. If a serious illness keeps you off work permanently, long-term cover pays out until you'd have retired. Higher premium, maximum security.
The definition that really matters
'Own occupation' pays out if you can't do your specific job. 'Any occupation' only pays if you can't do any work at all, which is a much higher bar. We always look for own occupation cover first.
See how income protection can support a broader financial protection plan.
Read the guideWork through your monthly bills, savings and sick pay to understand how much cover you may need.
Read the guideLearn when to contact your insurer, which documents to prepare and what happens during a claim.
Read the guide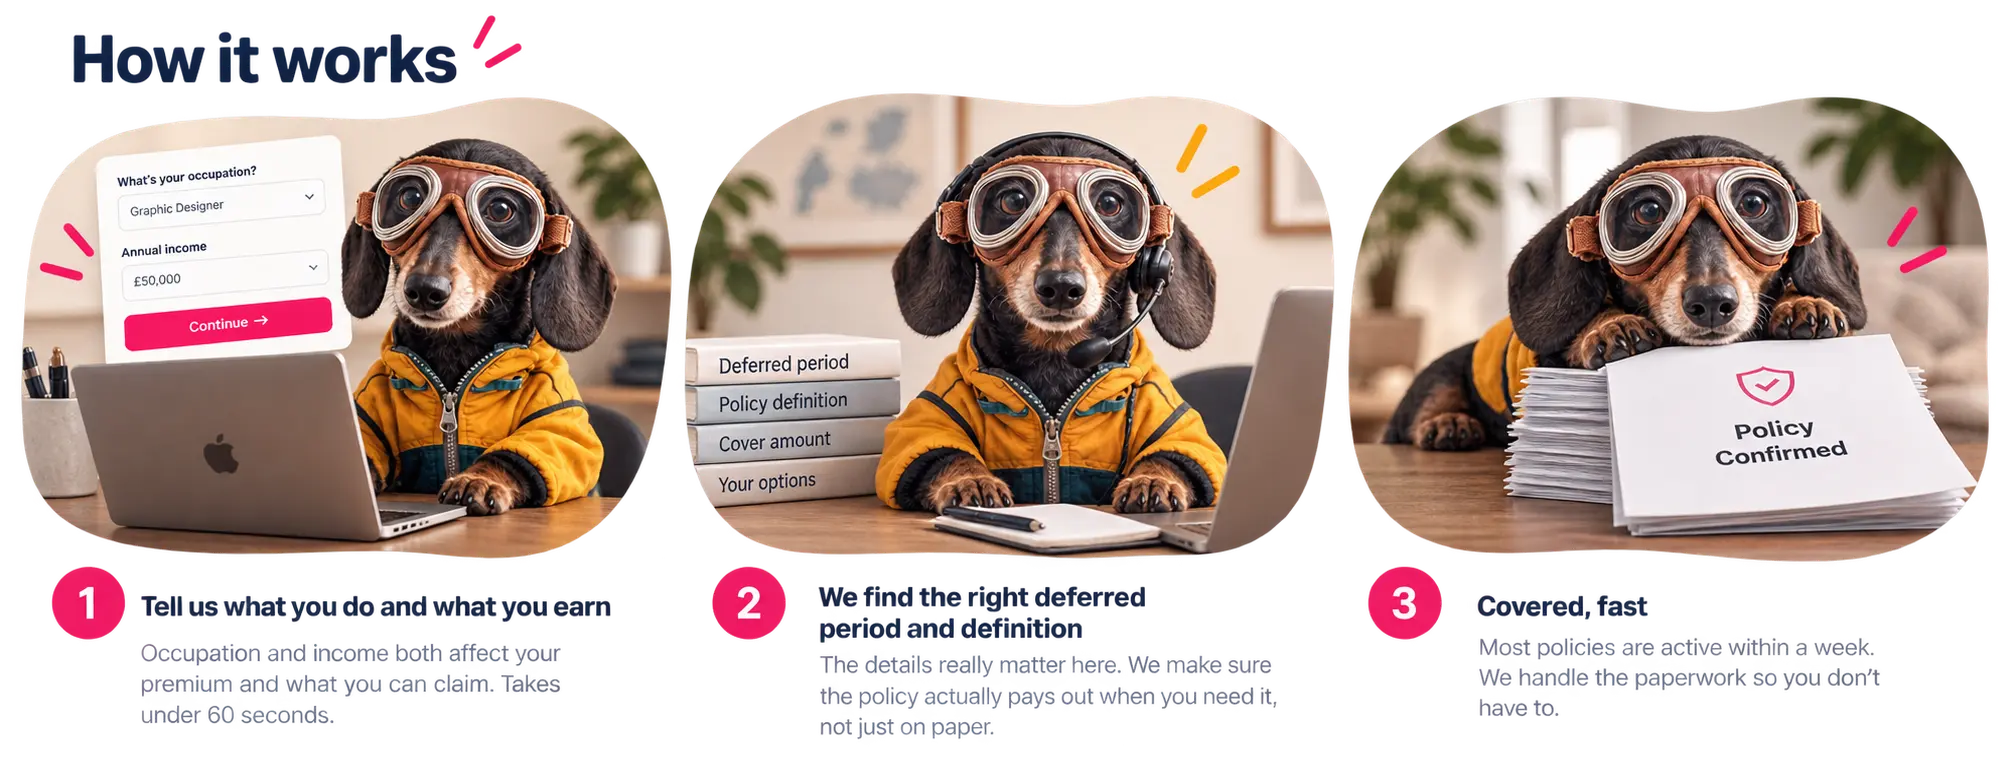
We do not guarantee a specific premium or that cover will be offered. Eligibility and underwriting decisions are made by the insurer. Always read your policy documents carefully.
Start your income protection quote online and we'll help find the right policy for your occupation and budget.

This is an advised service
One of our advisers will talk through your circumstances and give you a personal recommendation based on your needs and budget. We will explain why a policy suits you before you decide to go ahead.
Understanding your demands and needs
Before we arrange any cover, we will ask about your situation so we understand what you need the policy to do. Any cover we put forward is based on the information you give us, so please make sure it is accurate and complete.