Utterlycovered dog mascot
    UtterlyCovered Logo

    Protect yourjourney withcar insurance

    Car cover explained in plain English.
    Request a callback to discuss your options.

    Speak to our car insurance team
    Helpful UK teamFriendly, human support
    Cover explainedKnow what's included
    Clear, honest guidanceNo jargon, no pressure
    Your car, your needsUnderstand your options

    Protect what matters

    4 reasons to consider Utterlycovered car insurance

    From everyday journeys to unexpected incidents, the right cover starts with understanding what your policy does — and doesn't — include.

    car insurance

    Get started today

    Request a callback about your car insurance. We arrange cover on a non-advised basis, so you decide whether a policy meets your needs. No obligation to proceed.

    Your data is secure. We never sell your details.

    1. Meet your legal responsibilities

      You need at least third party motor insurance to drive on UK public roads. It covers your liability for injury to other people and damage to their property, subject to the policy terms.

    2. Protect your car as well as others

      Comprehensive insurance can cover damage to your own vehicle as well as third party liability. Third party, fire and theft adds cover for insured fire damage and theft, but not accidental damage to your own car.

    3. Prepare for an unexpected interruption

      A courtesy car, breakdown cover or legal expenses cover may help after an incident, but these aren't automatically included. Check availability, limits and conditions, and avoid paying for cover you already have.

    4. Match the policy to your driving

      Your mileage, vehicle, drivers and use of the car all matter. Check that commuting or business use is covered if needed, declare modifications accurately and choose an excess you could afford to pay.

    Before you choose / Read the quote

    Same car.
    Different small print.

    A cover label is only the starting point. When you look at a quote, ask these two questions.

    1. What is the full cost?

      Look at the total payable over the year, including any fees. If you pay in instalments, check any interest or charges rather than comparing the monthly payment alone.

    2. What if my plans change?

      Check any fees for changing your car or address, and the cancellation terms. Any refund depends on the terms and circumstances. Check whether the policy renews automatically and how to opt out.

    Clear explanations from Utterlycovered. Our service is non-advised: we explain the information; you decide whether the policy meets your needs.

    Explore the three cover levels

    "Sorted my car cover online in minutes. Really simple."

    Priya S., LeicesterCar Insurance

    What is car insurance and why do you need it?

    Car insurance is a contract between you and an insurer that protects you financially if something happens to your vehicle or you cause damage to others while driving. In the UK, having motor cover is not optional. It is a legal requirement under the Road Traffic Act 1988.

    Without valid cover, you could face serious consequences including a fixed penalty of £300 and 6 penalty points, prosecution in court with an unlimited fine, having your vehicle seized and potentially crushed, and invalidation of your driving licence.

    Beyond the legal requirements, motor insurance provides essential financial protection. If you're involved in an accident, your policy can cover repair costs, medical expenses, and legal liability, costs that could otherwise run into tens of thousands of pounds.

    Know your cover before you choose

    Key facts about car insurance in the UK

    The legal minimum is only the starting point. Look at what is covered, what is optional and what you would pay if you claimed.

    02 / Cover levels

    Three levels. Different protection.

    Policy terms, limits and exclusions still matter at every level. Comprehensive does not mean that everything is covered.

    1. Third party only

      Covers your liability for injury to other people and damage to their property, subject to the policy terms. It does not cover damage to, or theft of, your own car.

    2. Third party, fire and theft

      Adds cover for insured fire damage and theft of your car. Accidental damage to your own car is not generally included.

    3. Comprehensive

      Also covers insured accidental damage to your own car. Check the excess, repair arrangements and any conditions; driving other cars, a courtesy car or windscreen cover may not be included.
    03 / No-claims bonus

    A discount, not a promise about the price.

    A no-claims bonus, also called a no-claims discount, can build up through claim-free years. The discount, maximum years recognised and effect of a claim vary by insurer. A new provider may ask for proof of your existing bonus.

    Protected bonus does not mean a fixed premium. Protection may preserve your discount after certain claims, within the policy's limits. The underlying premium can still rise, including after a claim.

    04 / Optional extras

    Check what is included before adding more.

    Breakdown assistance, legal expenses, courtesy cars, windscreen cover and enhanced European driving cover may be included, optional or unavailable. Check the wording rather than assuming.

    • Would a courtesy car be available after theft or a write-off, or only during an approved repair?
    • What limits, excesses and conditions apply to each extra?
    • Do you already have equivalent cover through another policy or membership?
    05 / Cost factors

    Your premium starts with your circumstances.

    Insurers consider your age and driving experience, claims and convictions, occupation, postcode, where you park, annual mileage and how you use the car. The vehicle's type, value, security and modifications matter too.

    Your chosen cover, optional extras and excess also affect the quote. A higher voluntary excess may reduce the premium, but check the total you would need to pay towards a claim, including compulsory excesses.

    06 / A personalised price

    There is no single average price that tells you what your cover will cost. Request a quote based on your own details and check the total cost, including any charges for paying in instalments.

    Talk through your car insurance options

    Types of Car Insurance Explained

    There are three main types of motor cover available in the UK. Understanding the differences between these levels will help you choose the right protection for your needs and budget.

    Third Party Only (TPO)

    Third party only is the minimum legal requirement in the UK. This cover pays for damage you cause to other people, their vehicles, and their property. However, TPO does not cover any damage to your own vehicle.

    • Covers third party injuries
    • Covers third party property damage
    • No cover for your own vehicle

    Third Party Fire & Theft (TPFT)

    Third party fire and theft includes everything in TPO, plus protection if your car is stolen or damaged by fire. This is a popular mid-range option for many UK drivers.

    • All TPO cover included
    • Cover if your car is stolen
    • Cover for fire damage
    Most Popular

    Comprehensive

    Comprehensive offers the highest level of protection. It covers everything in TPFT plus accidental damage to your own vehicle, even if you're at fault. Often includes windscreen cover.

    • All TPFT cover included
    • Accidental damage to your car
    • Often includes windscreen cover
    Family with car - It feels good to be protected with the right car insurance cover

    Compare Cover Levels

    What's CoveredTPOTPFTComprehensive
    Third party injury claims✓✓✓
    Third party property damage✓✓✓
    Fire damage to your carNot covered✓✓
    Theft of your carNot covered✓✓
    Accidental damage to your carNot coveredNot covered✓
    Windscreen coverNot coveredNot coveredOften included
    Personal belongings coverNot coveredNot coveredOften included

    Why get your car insurance with UtterlyCovered?

    Request a callback and our UK team will explain the car insurance options available. We arrange cover on a non-advised basis, with clear information to help you decide.

    Request a callback online

    Leave a few details online and our team will contact you to discuss the cover you need.

    Clear cover information

    We set out what's covered, what's not, and where add-ons make sense. No confusing jargon, just clear information.

    Own-branded cover

    Your policy is arranged through UtterlyCovered, so you have one place to go for your cover and renewal.

    Here to help

    If you have a question about your cover, our friendly team is here to help. No pressure, no pushy sales.

    How Much Does Car Insurance Cost in the UK?

    Motor cover costs vary significantly based on your personal circumstances. The average UK premium ranges from £300 to £1,500 per year, but your actual cost will depend on various factors specific to you and your vehicle.

    Average UK Premiums (2024-2025):

    • • Young drivers (17-24): £1,200 - £2,500+
    • • Experienced drivers (25-65): £300 - £800
    • • Senior drivers (65+): £400 - £900

    Note: These are indicative ranges only. Your quote will be based on your individual circumstances.

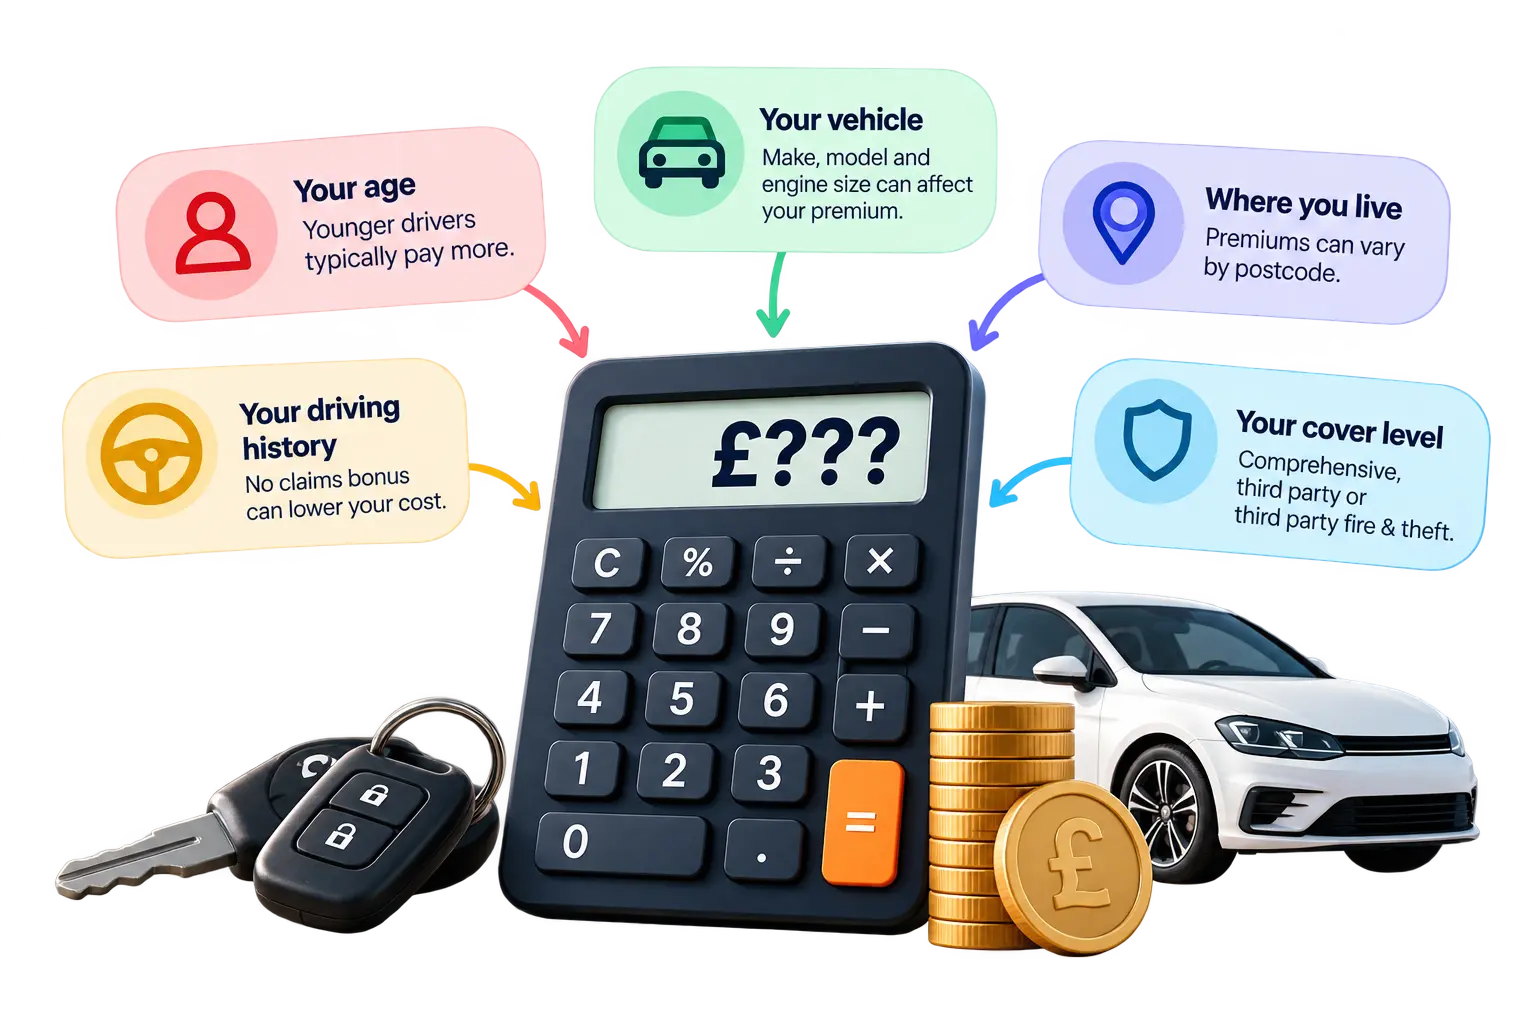
    Car insurance cost calculator showing factors that affect your premium

    What Affects Your Premium?

    Insurance providers use many factors to calculate your premium. Understanding these factors can help you find ways to reduce costs.

    Driver Profile

    Your age, driving experience, licence type, claims history, and any convictions all affect your premium.

    Vehicle Details

    Your car's make, model, engine size, insurance group rating, value, and any modifications impact your cost.

    Location

    Your postcode affects your premium based on local crime rates, traffic density, and claims history in your area.

    Usage Patterns

    Annual mileage, use for commuting or business, and where you park overnight all influence your premium.

    How to Reduce Your Premium

    There are several proven strategies to help lower your motor cover costs without compromising on the protection you need. Here are our top tips.

    Ways to Lower Your Cost

    • Build your no-claims bonus: Each year without a claim can earn you a bigger discount on your premium.
    • Increase your voluntary excess: A higher excess can reduce your premium, but make sure you can afford it if you claim.
    • Improve vehicle security: Fitting approved alarms, immobilisers, or trackers can reduce your costs.
    • Park securely: Keeping your car in a garage or on a driveway rather than on the street can lower your premium.
    • Review your cover at renewal: Checking your cover each year helps make sure it still suits your needs and circumstances.
    • Consider telematics: Black box policies can reward safe driving with lower premiums, especially for young drivers.

    Things That Increase Your Cost

    • Previous claims: Making claims can increase your future premiums.
    • Driving convictions: Penalty points and convictions will usually increase your costs.
    • High-performance vehicles: Cars in higher insurance groups typically cost more to insure.
    • Modifications: Most modifications will increase your premium. Always declare them.
    • High mileage: The more you drive, the higher your premium is likely to be.
    • Young or new drivers: Less driving experience typically means higher costs.

    Car Insurance for Different Drivers

    Young Driver Cover

    Young drivers typically pay more due to lack of experience. Consider telematics policies to reward safe driving and build a no-claims bonus.

    Learn more about young driver cover →

    Learner Driver Cover

    Learner drivers need cover to practice legally. Short-term learner policies or adding a learner to an existing policy are common options.

    Learn more about learner driver cover →

    New Driver Cover

    Just passed your test? Options include telematics policies and adding named drivers to help reduce your premium.

    Learn more about new driver cover →

    Over 50s Cover

    Experienced drivers often benefit from strong no-claims bonuses. Look for cover that recognises your driving experience.

    Learn more about over 50s cover →

    Business Use Cover

    If you use your car for work beyond commuting, you may need business cover. Make sure your policy explicitly covers your work-related driving.

    Learn more about business use cover →

    Multi-Car Policies

    Got more than one car? Multi-car policies can offer discounts when you insure multiple vehicles with the same provider.

    Learn more about multi-car policies →

    Add-ons and Optional Extras

    Many insurers offer optional add-ons to enhance your cover. These extras can provide additional protection but will increase your premium. Consider which add-ons offer genuine value for your circumstances.

    Breakdown Cover

    Get roadside assistance if your car breaks down. This add-on can include home start, national recovery, and European breakdown cover.

    Courtesy Car

    A courtesy car add-on provides you with a replacement vehicle while your car is being repaired following an insured claim.

    Legal Expenses Cover

    This add-on covers legal costs if you need to pursue a claim for uninsured losses following an accident that wasn't your fault.

    Protected No-Claims Bonus

    Protect your no-claims bonus even if you make a claim. This can help keep your future premiums lower.

    European Driving Cover

    Extend your cover when driving in Europe. This add-on provides the same level of protection you have in the UK when travelling abroad.

    Personal Accident Cover

    Provides a payout if you or your passengers are injured or killed in an accident, regardless of who was at fault.

    Telematics (Black Box) Car Insurance

    Telematics, also known as black box cover, uses technology to monitor your driving behaviour. A small device fitted to your car (or a smartphone app) tracks factors like speed, braking, cornering, and the time of day you drive.

    Safe driving can lead to lower premiums over time. This type of policy is particularly popular with young drivers and those looking to prove they're safe drivers to reduce their costs.

    Rewards safe driving with lower premiums
    Great for young and new drivers to reduce costs
    Helps build a track record of safe driving
    May include theft tracking and accident alerts
    Telematics car insurance UK - Black box cover for young drivers
    Making a motor insurance claim - Step by step UK guide

    Making a Claim

    If you're involved in an accident or need to make a claim, here's what you need to do. Following these steps will help ensure your claim is processed smoothly and quickly.

    1

    Ensure Everyone's Safety

    Check for injuries and call emergency services if needed. Don't admit fault at the scene.

    2

    Gather Information

    Take photos, note the time and location, collect other drivers' details and witness information.

    3

    Contact Your Insurer

    Report the incident to your provider as soon as possible via their claims line or app.

    4

    Follow Your Insurer's Guidance

    Your provider will guide you through the claims process and arrange repairs if needed.

    We search the UK's Leading Insurance Providers

    AXA logo
    RAC logo
    Royal London logo
    Scottish Widows logo
    Legal & General logo
    LV= logo
    Zurich logo
    Vitality logo
    Aviva logo

    Car Insurance FAQs

    Yes, motor cover is a legal requirement in the UK. You must have at least third party cover to drive on public roads. Driving without valid cover is a criminal offence that can result in fines, penalty points, and even having your vehicle seized. The only exception is if your vehicle has a Statutory Off Road Notification (SORN).

    The three main types are: Third Party Only (TPO), the minimum legal requirement that covers damage to others; Third Party Fire and Theft (TPFT), which includes TPO plus protection for fire damage and theft; and Comprehensive, the highest level of cover that also protects your own vehicle.

    You can reduce your premium by building up a no-claims bonus, choosing a higher voluntary excess, improving your vehicle's security, parking in a secure location, reviewing your cover at renewal, considering telematics or black box policies, and ensuring you only add genuine named drivers.

    A no-claims bonus (NCB) is a discount on your premium that you earn for each year you don't make a claim. Most providers offer up to 5 years of NCB, which can reduce your premium by up to 75%. You can also protect your NCB with an add-on, which may allow you to make a claim without losing your discount.

    Yes, modifications can significantly affect your premium. Any changes to your vehicle's appearance, performance, or security must be declared to your insurer. Common modifications include alloy wheels, body kits, engine tuning, and exhaust systems. Failing to disclose modifications could invalidate your policy.

    Some comprehensive policies include Driving Other Cars (DOC) cover, which provides third party only protection when driving someone else's vehicle with their permission. However, this is not standard on all policies and is typically limited to drivers over 25. Always check your policy documents to confirm.

    Most UK policies provide the minimum legal level of cover required in EU countries. However, for full comprehensive protection abroad, you may need to purchase European cover as an add-on. Since Brexit, you may also need a Green Card for some countries, so check with your provider before travelling.

    Telematics or black box cover uses a device or smartphone app to monitor your driving behaviour, including speed, braking, cornering, and the time of day you drive. Safe driving can lead to lower premiums. This type of policy is particularly beneficial for young drivers and those looking to reduce their costs.

    Your excess is the amount you pay towards a claim. Compulsory excess is set by your insurer and cannot be changed. Voluntary excess is an additional amount you choose to pay. A higher voluntary excess usually means a lower premium, but you'll pay more if you claim. Choose a voluntary excess you can comfortably afford.

    Leave your details and our team will contact you to discuss your car insurance options. The time needed to arrange a quote depends on your circumstances and the information required.

    Request your car insurance quote

    Request a callback to discuss car insurance with our UK team. We will explain the cover and price before you decide whether to proceed.

    [Placeholder: confirm before launch] Cover is underwritten by [insurer to be confirmed].

    Ready to get a car insurance quote?

    Request a callback and we'll help you find the right cover.

    Request Your Callback

    Important service information

    Understanding your demands and needs

    Before we arrange any cover, we will ask about your situation so we understand what you need the policy to do. Any cover we put forward is based on the information you give us, so please make sure it is accurate and complete.

    The price you pay for your car insurance depends on your individual circumstances and the cover you choose. Any premium figures shown on this page are for general guidance only and are not a quote. Your actual price will be confirmed when our team arranges your quote.

    UtterlyCovered

    An insurance advice and arrangement service helping families and individuals find suitable cover at competitive prices.

    Quick Links

    Contact Us

    talktous@utterlycovered.com
    3rd Floor Capital Tower
    Greyfriars Rd
    Cardiff CF10 3AG

    © 2026 UtterlyCovered.com. All rights reserved.

    UtterlyCovered.com is a trading style of Im-Insured.com Limited. Im-Insured.com Limited is authorised and regulated by the Financial Conduct Authority under reference 534183. You can check this on the Financial Services Register at register.fca.org.uk. Registered in England and Wales, company number 07325662. Registered office: 3rd Floor, Capital Tower, Greyfriars Road, Cardiff, CF10 3AG.